


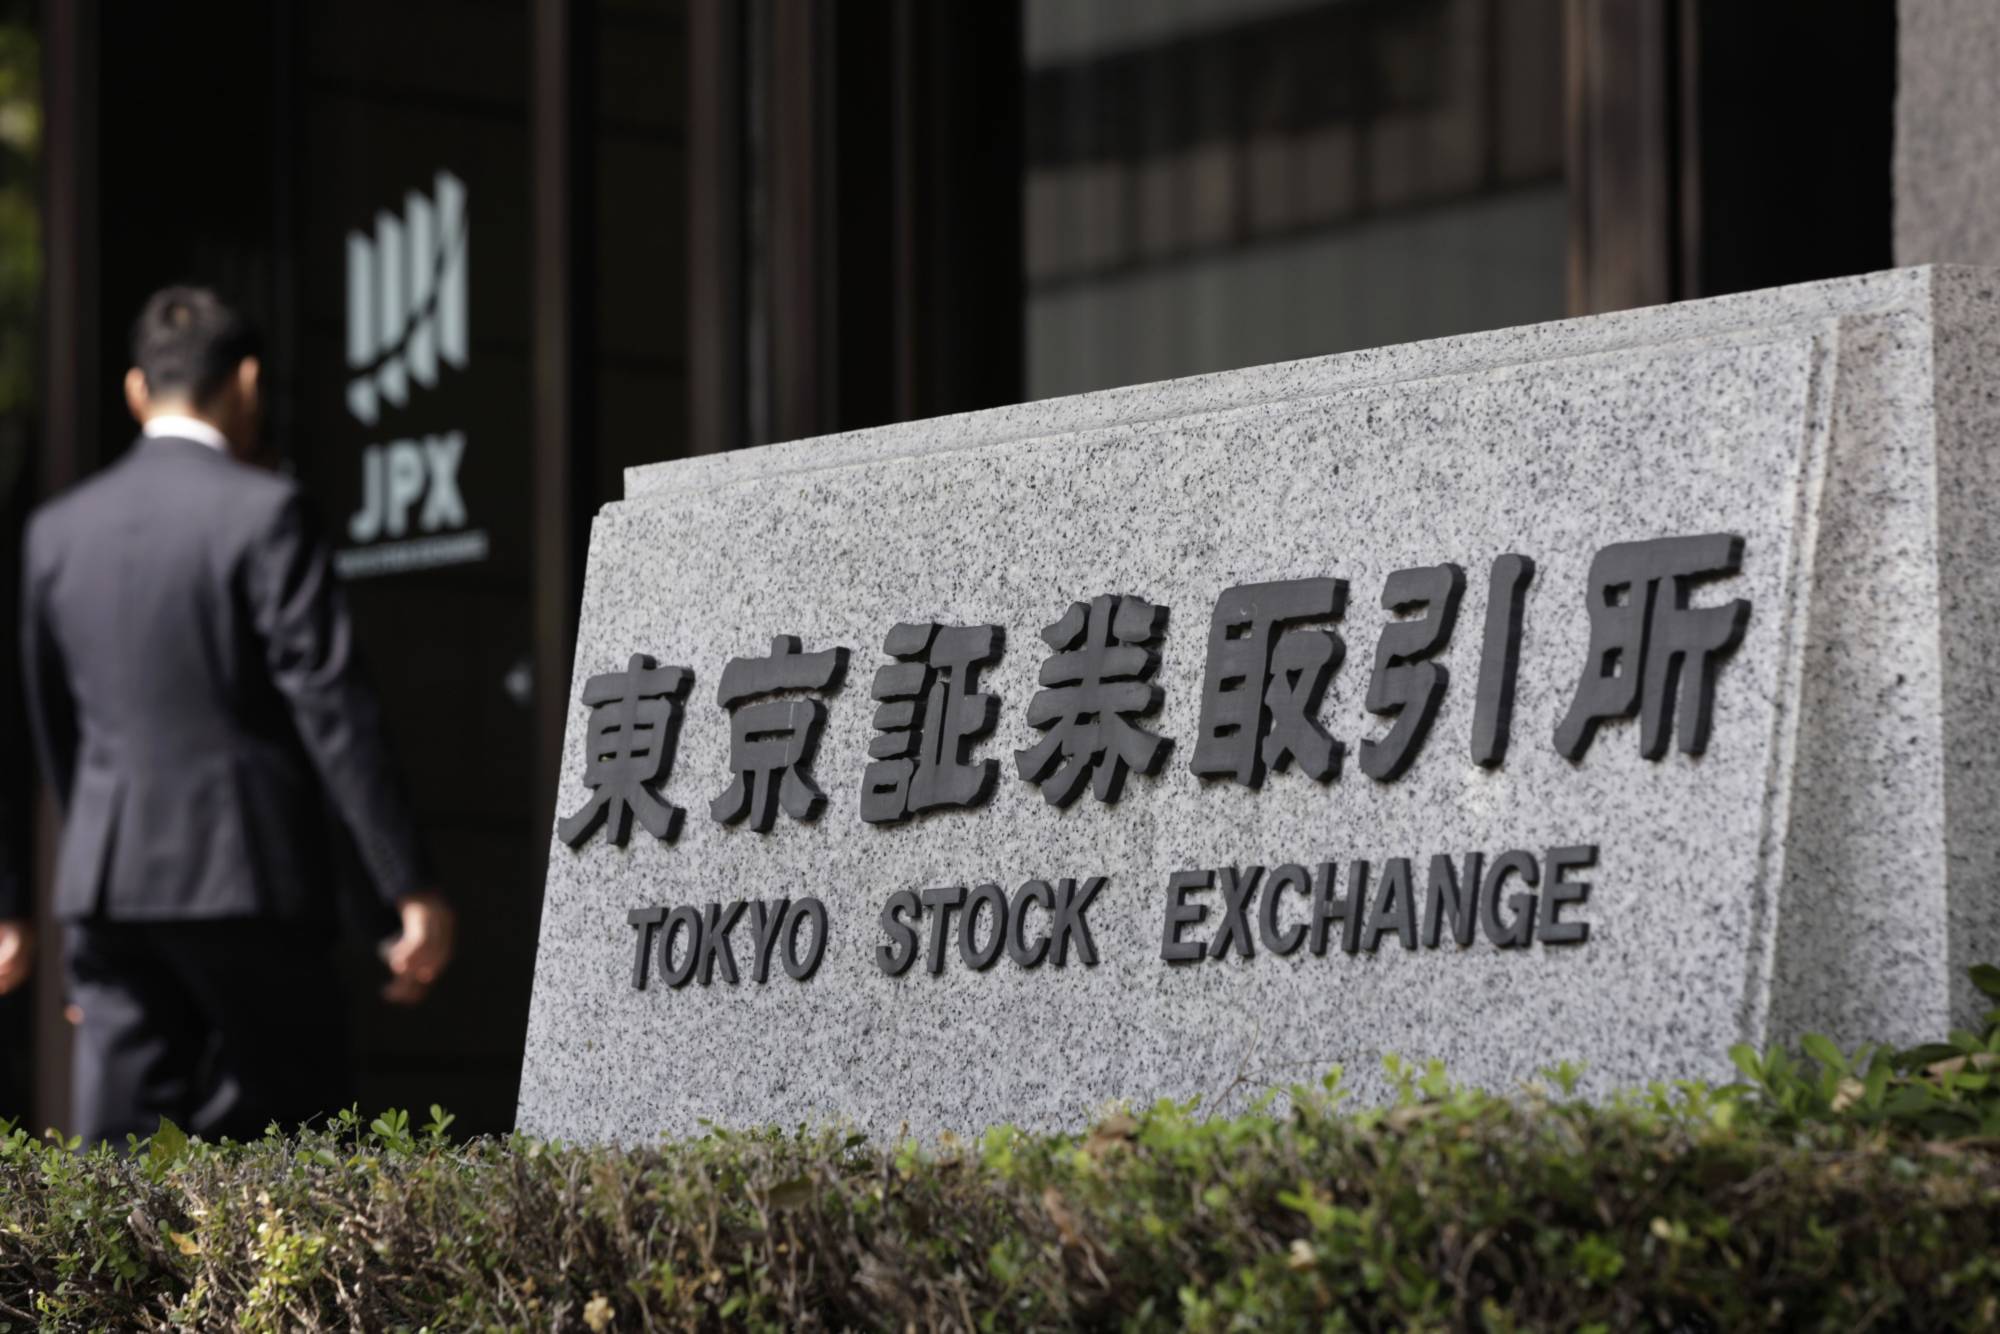
In the face of growing global competition among stock exchanges — and a rising sense of need to change its corporate culture — Japan is reforming its stock markets to attract more long-term investors.
Next April, the Japan Exchange Group will reorganize the market structure of the Tokyo Stock Exchange from its current four markets — First Section, Second Section, Mothers and JASDAQ — to three markets named Prime, Standard and Growth.
The reforms intend to increase the attractiveness of the flagship Prime market by setting more stringent minimum financial requirements on profits, net asset size and tradable market capitalization. The change is in response to investors’ long-standing criticisms that the First Section included several less liquid, small-cap stocks as well as companies that are not taking corporate governance seriously.
Two further notable changes will be applied to all listed companies, which could contribute to improving Japan’s corporate governance.
First, cross-shareholding will no longer be considered as tradable stocks. Cross-shareholding refers to strategically held stocks among suppliers and client companies — it is one of corporate Japan’s practices that has long been criticized by foreign investors for several reasons. For a long time, cross-shareholding was viewed as a practice that prevented takeovers from foreign companies, disregarded minority shareholders and made corporate boards conservative — leading to lower profitability compared to American and European companies.
KEYWORDS
In a time of both misinformation and too much information, quality journalism is more crucial than ever.
By subscribing, you can help us get the story right.
With your current subscription plan you can comment on stories. However, before writing your first comment, please create a display name in the Profile section of your subscriber account page.