


Forecasts for a second year of strong global growth face two main dangers: the health of China’s economy and the prospect of much higher U.S. interest rates.
How the world’s commercial poles navigate these risks will determine whether 2021’s rapid expansion was a blip or whether the recovery will outlive the pandemic.
China appears determined to quash — rather than live with — COVID-19. An overly muscular economic response, too, may do as much harm as good. Forces unleashed by the disease, such as supply chain snarls that are pushing prices higher and shutdowns of major Chinese cities won’t dissipate overnight. Success will hinge on the ability to be nimble.
China reported Monday that gross domestic product rose 4% in the fourth quarter from a year earlier, down from the 4.9% initially recorded in the preceding three months. While better than many economists anticipated, we have become so accustomed to exceptionalism that a “4” handle rates as a disappointment.
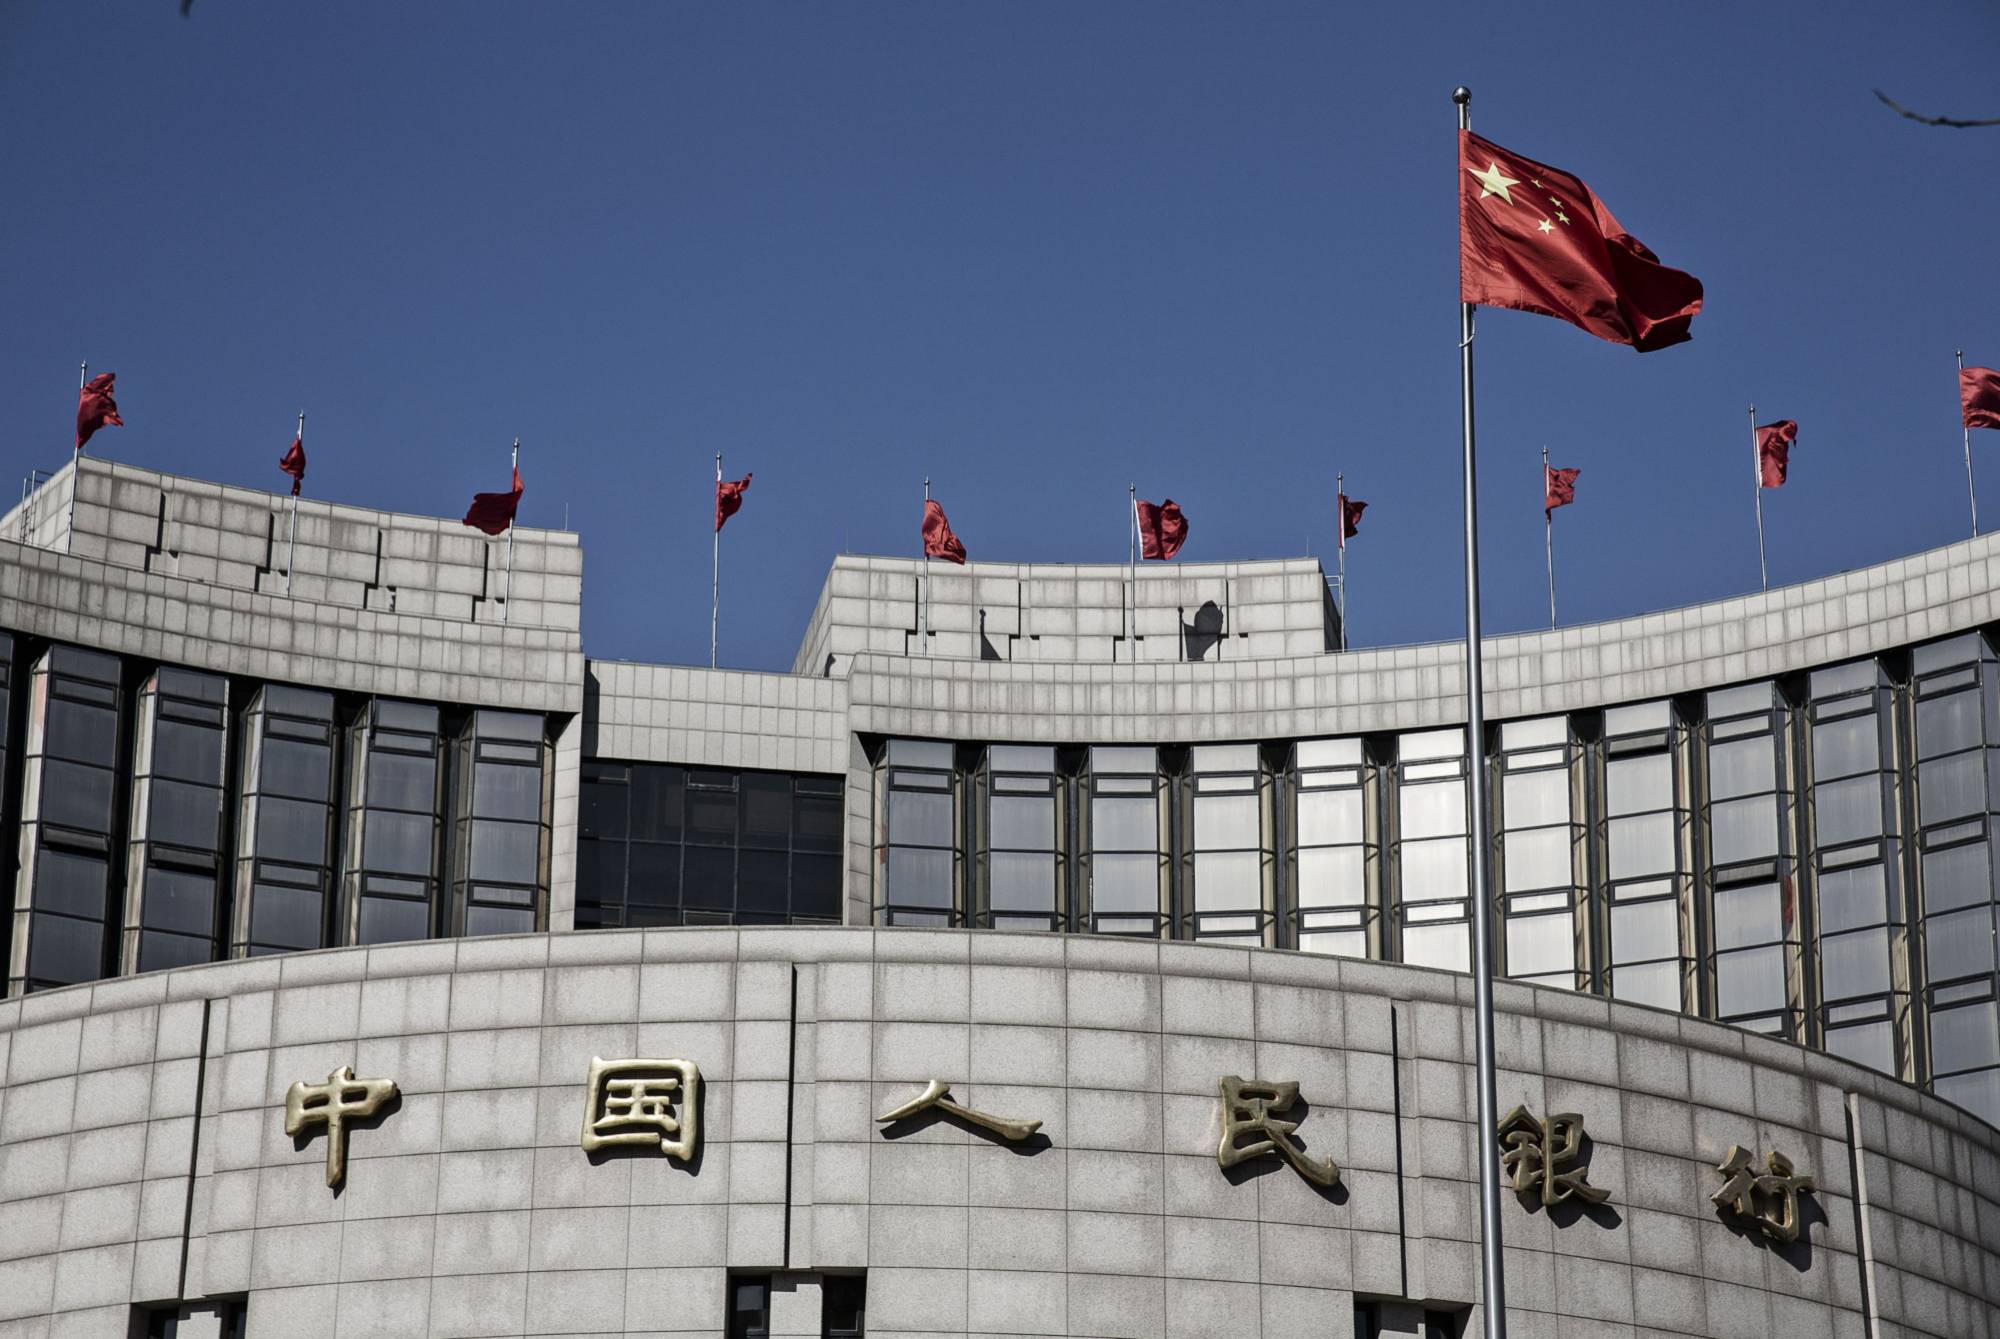
Less than an hour before the GDP numbers were released, the People’s Bank of China lowered a key rate for the first time since April 2020. This kind of light-footedness, simultaneously curtain-raiser and response, needs to be a big feature in the coming year. For Beijing, the risks of too tepid a response are significant. The relative modesty of the reduction — 10 basis points to 2.85% — shouldn’t obscure the symbolism.
KEYWORDS
In a time of both misinformation and too much information, quality journalism is more crucial than ever.
By subscribing, you can help us get the story right.
With your current subscription plan you can comment on stories. However, before writing your first comment, please create a display name in the Profile section of your subscriber account page.